
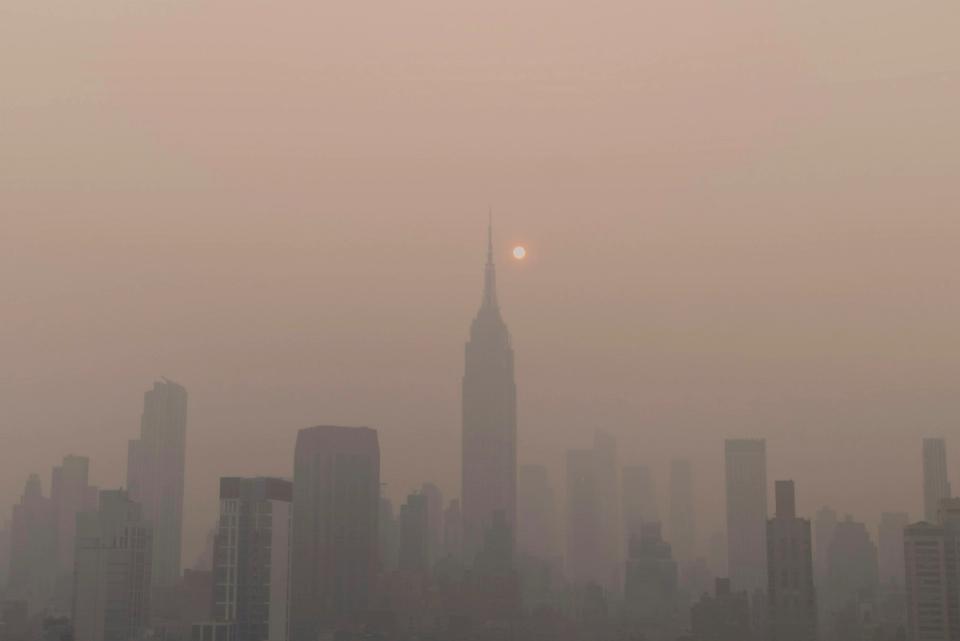
Wildfire risk and home insurance pricing in Canada
Home & Tenant Insurance
Reinsurance costs reach premiums far from any fire zone. How catastrophe risk enters home insurance pricing, and how to read the risk lines on a policy.
This hub is for one decision: whether the home or tenant policy in front of you covers the risks your address actually faces, and what to ask before the renewal is signed. Fire, including wildfire, is a standard peril on Canadian home policies; the questions worth asking are about the limits, the deductible, and the clauses that decide a claim after an evacuation, such as additional living expenses and the cost of rebuilding to today's code. Water is different: overland flood and sewer backup are usually endorsements you add, so a policy can be in force and still leave the basement uncovered.
The wildfire guide is the place to start if you live near forest or grassland anywhere in Canada; it explains what moves premiums in exposed areas and what a renewal letter is telling you when the deductible changes. Renters are covered here too: a tenant policy is mostly contents and personal liability, and the guide on what tenant insurance covers (in preparation) sets out what a landlord's policy does and does not do for the people living in the unit.
As with every TopRates hub, nothing here is a quote or a recommendation of an insurer. Each guide names its sources, the Insurance Bureau of Canada and the regulator among them, and keeps figures to those sources. For the mortgage side of owning the home, the hub hands off to TermRates.ca.
Home & Tenant Insurance
Reinsurance costs reach premiums far from any fire zone. How catastrophe risk enters home insurance pricing, and how to read the risk lines on a policy.
Home & Tenant Insurance
Reinsurance costs reach premiums far from any fire zone. How catastrophe risk enters home insurance pricing, and how to read the risk lines on a policy.
Fire, including wildfire, is a standard peril on Canadian home policies. What varies is the limit, the deductible and the clauses around an evacuation: additional living expenses, how long they pay, and whether the rebuilding cost is insured to today's code. Check those three on the renewal before assuming the coverage is enough.
Home premiums move with the insurer's view of the risk at your address and in your region, not only with your own claims. The wildfire guide walks through the public sources that show how insured losses have moved, and what to ask when a renewal raises a deductible or adds a condition.
A landlord's policy covers the building and the landlord's liability, not a tenant's contents or a tenant's own liability for damage or injury. A tenant policy fills that gap. The tenant insurance guide, in preparation for this hub, sets out what each side's policy does.
2 guides, newest first.
Home & Tenant Insurance
Liability is the part of a tenant policy that matters most, and the part renters think about least. What the three sections of a basic policy actually do.
Home & Tenant Insurance
Reinsurance costs reach premiums far from any fire zone. How catastrophe risk enters home insurance pricing, and how to read the risk lines on a policy.
Topics TopRates does not cover, on the Rate Family sites that do.